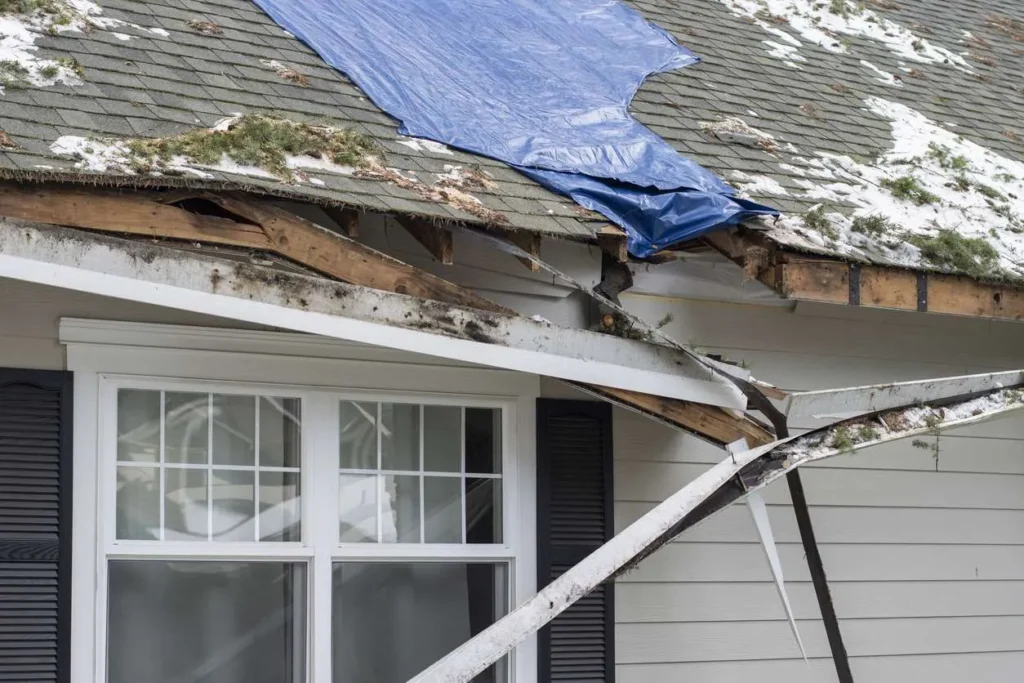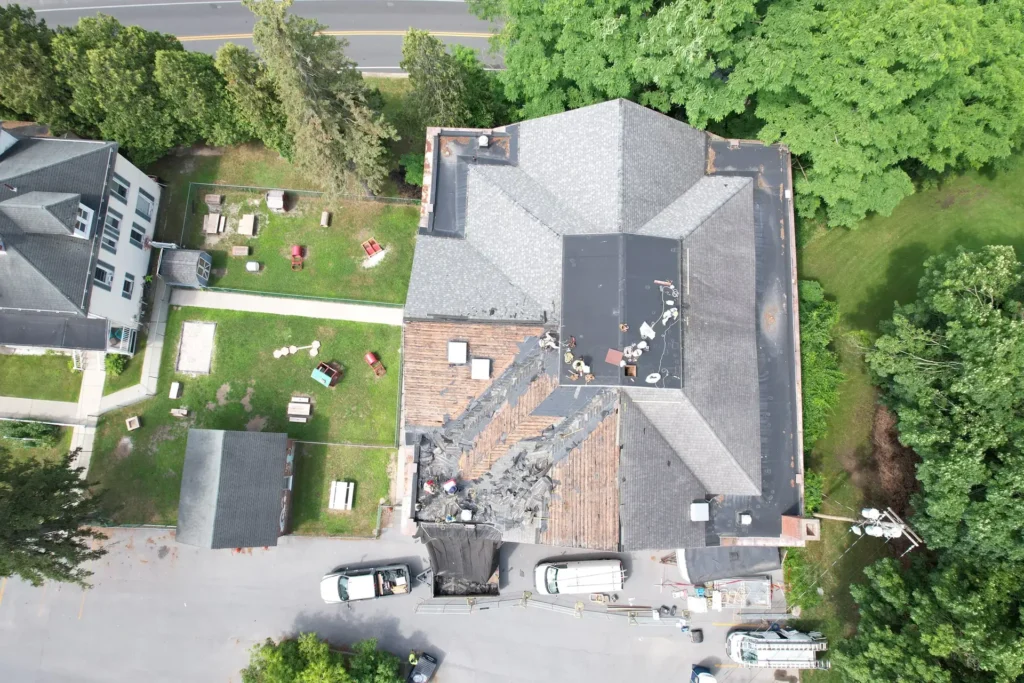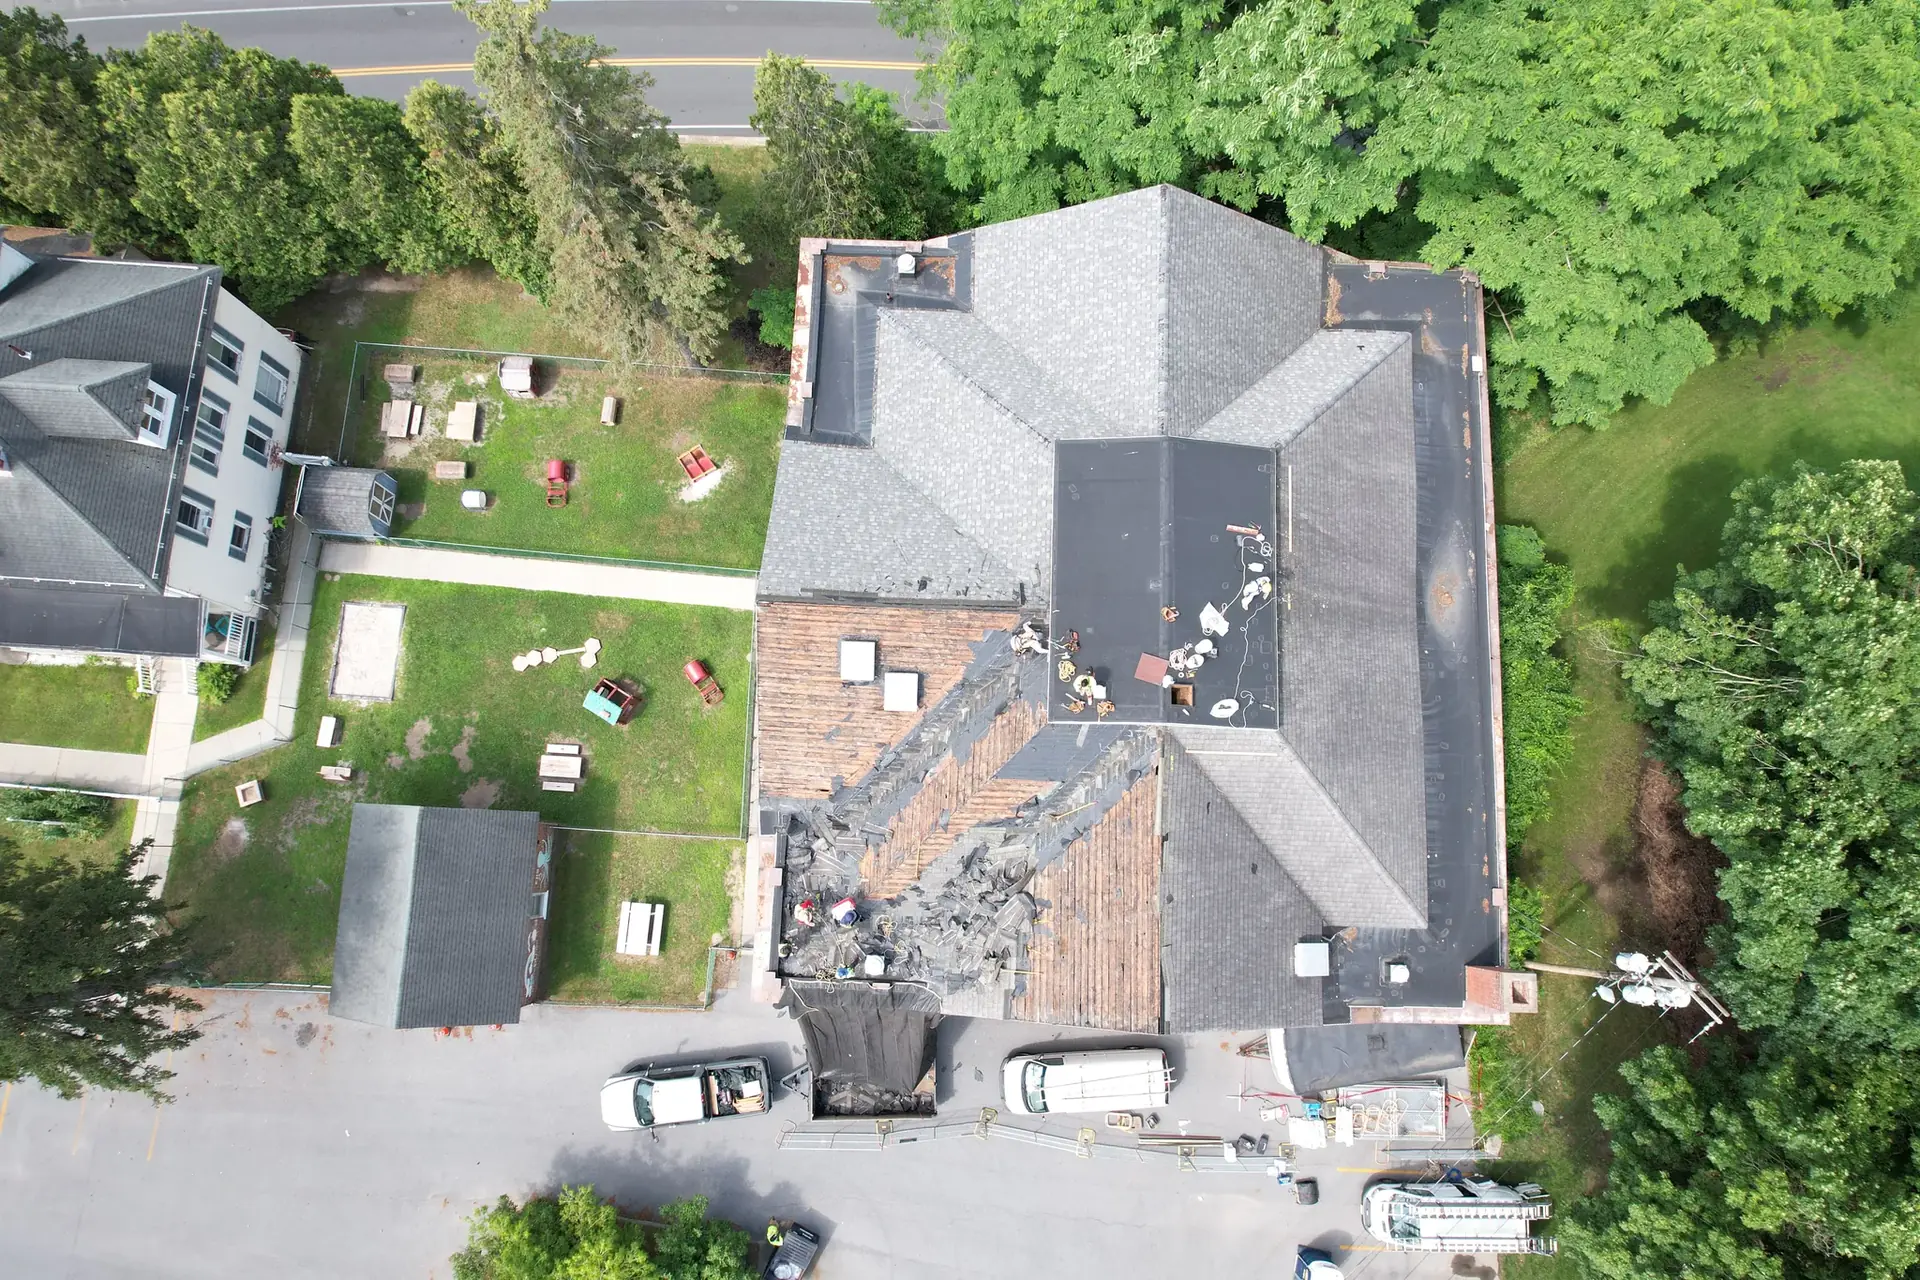
Bergen County storms don’t wait for a convenient time. Summer squalls, remnants of coastal systems tracking north, nor’easter tail-ends, and the occasional real tornado warning — all of it hits North Jersey rooftops hard. When your Bergen County home takes storm damage, the first 48 hours matter a great deal. Documentation, temporary protection, insurance timing, and vendor selection all get decided in that window.
Here’s the real homeowner’s action guide for the first 48 hours after roof storm damage in Bergen County — Hackensack, Paramus, Fair Lawn, Ridgewood, Teaneck, Fort Lee, Englewood, Bergenfield, and every town in between. From a licensed local general contractor that handles roofing, gutter, and siding storm response across Bergen and the surrounding counties.
First: Safety Comes Before Everything Else
Before you inspect anything, before you take photos, before you call anyone — safety first.
- Stay off the roof. Wet shingles, hail-damaged sheathing, hidden structural damage. Roof inspection after a storm is a professional job.
- Stay away from downed power lines. Assume every downed line is live. Call PSE&G or your utility, not your roofer.
- Check for gas leaks. If you smell gas, exit the house, call the gas company from outside.
- Watch for hidden water damage indoors. Sagging ceilings, wall bulges, water stains — these can precede structural collapse.
- Don’t enter attics with visible water intrusion. Wet insulation and drywall get heavy fast. Water-damaged rafters can fail without warning.
If any of these are present, the first call is the utility company and, if necessary, the fire department. The roofer comes after the immediate hazard is handled.
Hours 0–4: The Ground-Level Inspection
Once it’s safe to be outside, walk the property and document what you can see from the ground. This is not a climb-up-the-ladder exercise — everything visible from the ground counts as first-pass evidence for insurance.
- Look at each roof slope from the yard. Missing shingles show as dark patches. Displaced shingles curl at edges. Hail damage may not be visible from the ground but massive impact damage will be.
- Check the gutters and downspouts. Gutters filled with granules from shingles are a real signal of surface damage. Sagging or torn-away gutters indicate structural impact.
- Walk the perimeter of the house. Look for shingle pieces, granules, metal flashing, or roof debris on the ground. All of this is evidence.
- Photograph everything. Wide shots of each roof slope. Close-ups of debris on the ground. Any damaged siding, windows, doors, or trim. Timestamp matters — most phone cameras add this automatically.
- Check the interior ceiling in every room. Water stains, active drips, sagging spots. Note where water is coming from — this maps back to roof impact areas.
- Check the attic if safely accessible. Daylight visible through the roof deck is a serious sign. Wet insulation, water on rafters, or new water stains all matter.
Save every photo, every video, every note. The insurance adjuster’s first question will be about documentation from the moment of loss.
Hours 4–12: Call Your Insurance Company
Report the loss to your homeowner’s insurance company as soon as documentation is in hand. Most policies require prompt notice of a loss, and late notice can complicate a claim. Check your policy for its reporting requirements.
- Have your policy number ready.
- Report the date and time of the storm. The county-wide weather event helps your case. NOAA’s New York area weather forecast office covers Bergen County and maintains storm records that support claims.
- Describe the damage in specifics. Missing shingles, water in the ceiling, damaged siding, damaged gutter — the more concrete, the better.
- Ask about your deductible and coverage limits. Some policies have a separate wind or hail deductible.
- Get a claim number. Write it down. Every subsequent communication references it.
- Ask when the adjuster will inspect. After a widespread storm adjusters can be busy, so the inspection may take longer than usual. Ask what temporary protection you’re allowed to install without voiding coverage.
Insurance basics matter here. Most policies cover sudden storm damage but not gradual deterioration. Documentation of the storm event and the fresh damage protects you from a “pre-existing wear and tear” denial.
Hours 12–24: Temporary Protection
If your roof has active leaks or exposed structure, temporary protection prevents secondary damage while you wait for a permanent repair. This is where a local licensed roofer earns their keep.
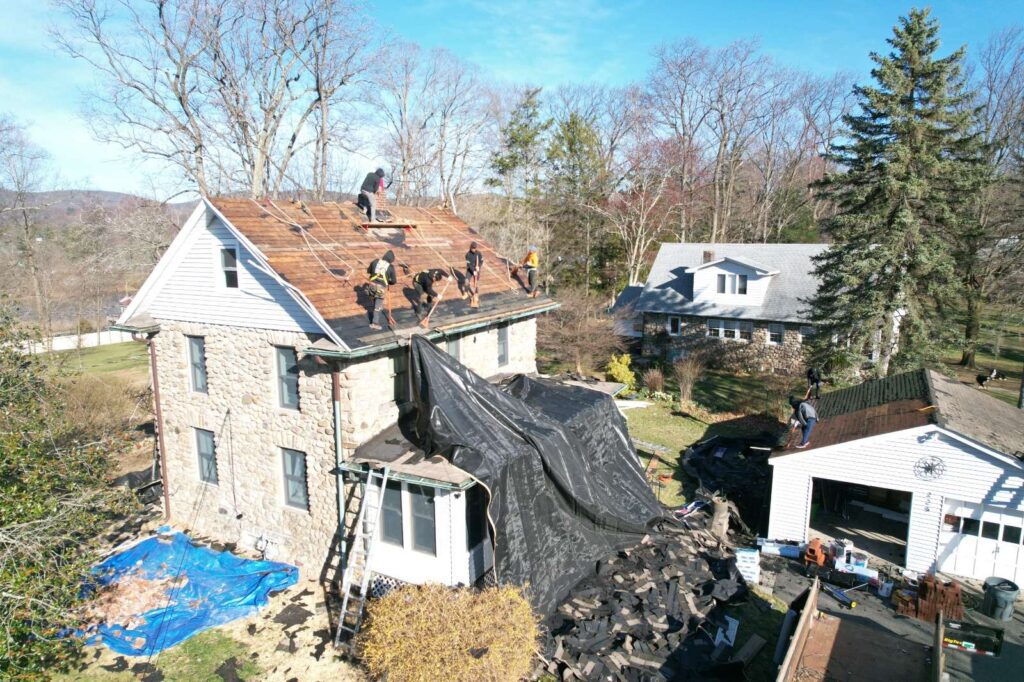
- Emergency tarping. Professional tarping is the standard temporary measure. Done right, a tarp secures a damaged section and prevents further water intrusion for weeks.
- Do NOT climb on a wet or storm-damaged roof yourself. Falls from ladders and roofs cause serious injuries every year.
- Get the tarping price and scope in writing. Be cautious with anyone who pressures you to sign a full repair contract along with the tarp, or who cannot show a registration and insurance certificate.
- Verify the licensed local roofer before signing anything. New Jersey home improvement contractor license. Real business address. Real insurance certificate. Real reviews from local jobs.
- Get the temporary protection cost in writing. Ideally separately from the permanent repair estimate — many insurers reimburse temporary protection as a separate line.
Our post on 5 signs your roof needs replacement covers what the underlying damage patterns actually look like once the storm response is over.
Hours 24–48: Get Multiple Real Estimates
Once temporary protection is in place, start the estimate process for the permanent repair or replacement.
- Get 2–3 estimates from registered, insured contractors. Compare written, itemized scopes rather than the quickest offer.
- Get roofing, gutters, and siding estimated together if all three are damaged. Bundling matters — a single contractor handling all three services is easier to coordinate with insurance and easier to warranty afterward.
- Verify the license. New Jersey requires home improvement contractor (HIC) registration. Verify at the NJ Division of Consumer Affairs before signing anything.
- Verify insurance. Real general liability, workers’ comp, and roofing-specific coverage. Request a certificate of insurance with your name and address listed as certificate holder.
- Verify local addresses and phone numbers. Make sure you can confirm a real business address and a working phone number.
- Get the estimate in writing. Scope of work, materials, timeline, warranty, price. Verbal quotes are useless.
- Do NOT sign an Assignment of Benefits. This transfers your insurance claim rights to the contractor. Read any document carefully and talk to your insurer before signing one.
For the material decision itself, our post comparing metal vs. asphalt shingles covers the material tradeoffs for Northeast climates. For deciding whether to replace gutters at the same time, our post on replacing gutters when you replace the roof walks through when the bundle actually saves money.
Choosing a Contractor After a Storm in Bergen County
A knock on the door or an offer of a free inspection is not a warning sign by itself; Nuvista offers free inspections too. What matters is how a contractor does business. Watch for:
- Pressure to sign right away. A same-day discount, a “today only” price, or a contract pushed on you before you have had time to compare estimates.
- Missing credentials. No verifiable New Jersey Home Improvement Contractor registration, no certificate of insurance, or no business address you can confirm.
- Unclear pricing or scope. No written, itemized estimate showing the work, the materials, the price and the payment schedule.
- Requests to sign over your claim or pay everything up front. An Assignment of Benefits before you have an itemized estimate, or full payment before the work starts.
Bergen County residents can verify contractor complaints and license status through the NJ Division of Consumer Affairs before signing anything. The Bergen County government website provides local resources and consumer protection contacts.
What Insurance Typically Covers (And What It Doesn’t)
Typically Covered
- Wind damage from a documented storm event
- Hail damage with visible impact evidence
- Fallen tree damage from a storm
- Water damage inside the home caused by roof failure during a covered event
- Damaged gutters, siding, windows, or trim from the same storm event
- Emergency tarping and temporary protection (often reimbursed, depending on the policy)
Typically NOT Covered
- Gradual wear and tear on an older roof
- Damage from delayed maintenance (a roof that should have been replaced years ago)
- Claims complicated by late notice (check your policy’s reporting requirements)
- Damage not covered by your specific policy (some newer policies exclude cosmetic hail damage on metal roofs)
- Water damage inside the home if the roof was not compromised by the storm
Every policy is different. Read yours or ask your agent. If your Bergen County roof is 20+ years old and hasn’t been inspected, storm damage claims get complicated fast.
If Gutters or Siding Are Also Damaged
Big Bergen County storms rarely damage only the roof. Gutter and siding damage often happens in the same event.
- Gutters: Sagging, torn-away, or blocked with roof debris. Damaged gutters can cause secondary water damage to fascia, soffit, and foundation.
- Siding: Wind-torn panels, hail-cracked sections, impact damage from windborne debris. Damaged siding lets water into wall assemblies — a hidden but real problem.
- Windows and doors: Broken glass, damaged frames, water infiltration around openings.
- Flashing and trim: Metal roof flashing, chimney flashing, and trim can all be affected in high wind events.
Bundling roofing, gutter, and siding repairs into one project has real advantages — one contractor, one schedule, one warranty, one insurance conversation. Our post on when siding needs replacement covers the siding side, and the gutter replacement decision is covered in the gutter and roof post linked above.
The 48-Hour Checklist
- ☐ Safety check complete. No downed lines, no gas leaks, no structural imminent-collapse risks.
- ☐ Ground-level inspection photographed and documented.
- ☐ Interior water damage photographed and documented.
- ☐ Insurance company notified. Claim number in hand.
- ☐ Every contractor checked for registration, insurance and a written, itemized scope.
- ☐ Licensed local roofer contacted for temporary protection if actively leaking.
- ☐ 2–3 written estimates in process for permanent repair.
- ☐ HIC license verified for each estimate.
- ☐ Insurance certificates verified for each estimate.
- ☐ Bundled roofing/gutter/siding estimate if multiple systems damaged.
Local Bergen County Storm Response
If your Bergen County home took storm damage — roof, gutters, siding, or all three — Nuvista handles storm response across the county. We’re a licensed New Jersey general contractor with real insurance, a real Bergen-area presence, and experience running the full storm-damage claim process alongside residential roofing, gutter, and siding work. We handle residential roofing, gutter replacement, and siding installation as a bundled scope when the storm hits all three.
If you need a real inspection, a written estimate, or help thinking through the insurance claim process, request a free estimate — we’ll walk the property, put together a written scope, and give you the honest read on what the storm actually did.